Welcome, and thank you for your visit.

*Personal Branding Accelerator* Internet Lead Generation Coach*Digital Printing* Graphic Business* Out of Home wide format Printing* Billboard Banner* Brokerage* E Marketing* Western Eastern Europe* Middle East Africa* Corporate Account management* Sales Coaching* Brand Coaching*Negotiation skills.*Help software companies globalize their solutions

Lucien Moons Business Accelerator current mission with Scitexvision-NUR-Colorspan (Now a HP company since Nov 2005) is to market High Volume large format digital printers and help accelerate the analogue to digital revolution for silk screen, offset and packaging companies in Central Eastern Countries. (Pol, CZ SK HU RO SLO Cro BH Ser Mace Bulg.)


Tuesday, August 10, 2010

Printer’s Survival Kit: Understand & Participate in the Digital Economy

By Jennifer Matt
Published: August 10, 2010
Print is a major player in the information business. Everything that is printed communicates information for various purposes, including promotion, entertainment, education, transaction, etc. Today's digital technologies are changing virtually everything about the information business.
The information business is simultaneously operating in two economies - rapidly transitioning from the "atoms" based economy to the "bits" based economy. Nicholas Negroponte first introduced the concept of an "atoms" and "bits" economy in his 1996 book Being Digital. Negroponte stated that the world had been based on an economy of "atoms" (physical stuff that we dream up, manufacture, and distribute, a slow moving, "human handling" economy), whereas the future is about the "bits" economy or digital economy which is "...instantaneous and inexpensive transfer of bits at the speed of light."
Print is part of the atoms economy (physical stuff). In the atoms economy, we create content and distribute it via atoms (books, newspapers, magazines, mail, flyers, signage). Now the information business has a new distribution system, because virtually every product sold in the information business can be rendered in a digital form.
We advise printers to become marketing service providers in order to diversify from a 100% print manufacturing revenue stream. Negroponte would say that printers need to figure out a way to render a portion of their information products in digital form in order to participate in the bits economy. Atoms-based economies aren't going away-many of them cannot be rendered in a digital form (food, shelter, etc...) - but we work in the market that is most impacted by this monumental change because the entire information business is perfectly suited for digital distribution. Don't mistake the digital/bits economy with digital printing; all print is still very much atoms-based (physical stuff).
Remember all the hype in the 90's about the potential of the internet? Most of it had to do with the fact that we didn't understand the implications of a distribution system that is deflationary (the costs are rapidly decreasing). Yes, I'll say that again. The costs of distribution in the digital economy are getting cheaper, at a rapid pace. Chris Anderson, in his book Free, says, "racing towards the inevitable radical price of free." It will cost Google 50% less to stream that YouTube video next year (bandwidth costs); it will cost Google 50% less to host your Gmail account next year (storage costs).
In the 90's we thought we could reap the benefits of the bits economy simply by online-enabling procurement in the atoms economy (pets.com - dog food happens to be very heavy atoms). There's no way to render dog food into a digital product; hence, the only real efficiencies were in the ability for your customers to order online. Pets.com imploded because the world didn't need another atoms-based distribution system for dog food. On the other hand, Amazon thrives, because creating an unlimited inventory in the information market is a huge benefit even if you're shipping atoms. Now with the Kindle, Amazon has rendered its core product into a pure digital form to maximize its use of the digital economy. In July 2010, Amazon reported that Kindle sales (digital economy) now outpace books (atoms economy) for the company.

Two Economies
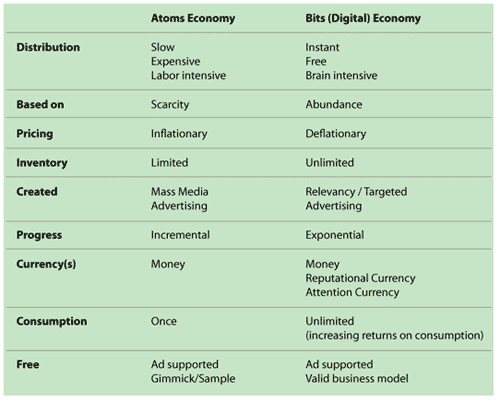
A distribution system that has unlimited inventory and whose cost of distribution is deflationary creates an economy based on abundance rather than scarcity. In the atoms-based information market, prices are based on scarcity; there are only so many TV spots you can sell during the Super Bowl, there is space for only so many ads in a magazine, etc. An abundant economy includes an unlimited number of books (Amazon), unlimited number of songs (iTunes), unlimited content (blogs, wikis, websites) because the cost of incremental additions is essentially too low to measure.
In 2006, Chris Anderson explained this brilliantly in his book, The Long Tail. What do unlimited inventories do to product selection and the whole idea of blockbusters? Because iTunes can provide music for the smallest niche - for example, one of my favorites - Indian Jazz Fusion - Anderson states that the Long Tail represents "...the end of the monopoly of the blockbuster, as hits are forced to share the stage with countless niche products targeting narrow consumer demand." Michael Jackson's Thriller album was a blockbuster partly because we had a limited inventory to choose from (the top 5,000 albums). Today we have access to our true niche tastes (e.g., the local band) because the digital economy allows companies to service the niche market as effectively as it serviced the mass market.
If you're feeling overwhelmed, put your seat belts on because the rate of change in the digital economy is exponential. The digital world combines incremental improvements with breakthrough inventions to give it a much steeper evolutionary curve. Moore's Law states: "...the number of transistors that can be placed on an integrated circuit has doubled approximately every two years," and is the most famous example of exponential progress in the digital world. Anderson points out, "the price of bandwidth and storage is dropping even faster."
The atoms economy is moving incrementally; the bits economy is moving exponentially. One side effect of these differences in pace is that the participants in each economy have different comfort levels with change. Bits economy people view change as ubiquitous and fast; atoms economy people see change as incremental and slow. One embraces change; the other is cautious and frequently resistant.
The software market is a good example. Today software is typically sold in two primary ways: On Premises License or Software as a Service (SaaS) Subscription. There is still an active debate in the print industry about licensing versus subscription which I have covered extensively at WhatTheyThink's The Web and Print blog. While we in the atoms based economy are debating this issue, the bits economy has evolved to yet another revolutionary invention that radically increases efficiencies and decreases costs of software deployment - cloud computing. Cloud computing is the ultimate global pooling of resources - rent only what you need (bandwidth, storage, processing power) in per minute increments. The US government estimates the average server utilization in its 1,100 data centers is 7%, an unbelievable amount of waste in several critical resource pools, power being the most obvious one. Pooling those resources in a cloud computing model would enable the government to pay for only the resources it consumes, representing an incredible savings in hardware, software, and energy.
While printers still grapple with decisions about On Premises versus SaaS, the digital economy is racing towards further optimization. Maybe one of the most important lessons we can learn from the bits economy is that we must embrace change or be left in the dust!

Free

Anderson's contribution in Free is the latest chapter of this story. He builds on Negroponte's atoms-versus-bits distinction and his own ideas around The Long Tail. Anderson brilliantly describes the results of the digital economy on the business model of Free: "While the last century's 'Free' was a powerful marketing method, this century's 'Free' is an entirely new economic model."
Abundance economy built on bits and a free distribution system creates a very different kind of free. Yes, we still have the ad-supported free. Google is the poster child for ad-supported "free to me" on the web. We think of Google as a software company, but Google has a very traditional media business model. The New York Times sells readers to advertisers (mass media); Google sells individual user intent to advertisers (relevance media). The advertisers on Google pay so that we can search for free. Traditional media companies keep saying online advertising is destroying their business. Online advertising is rapidly demonetizing the atoms-based information market because mass media is inefficient, bothering 90% of us to find the few who are interested in the product. Think denture commercials watched by your kids. Google's search delivers relevance at the individual level which is a better mouse trap AND it opens advertising up to a much bigger market.
The mass media approach had so much waste that only the deepest pockets could afford it. Today if you are a bonsai tree specialist in San Francisco, you can afford to advertise online because Google only charges you when someone clicks (very little waste).
Probably the most radical implication of this new economy is a viable business model that is based on giving your product/service away for free. Not the gimmicky free of yesterday, but a genuine free to most of the users of the solution forever. Thus the name "freemium" gets introduced into the Web 2.0 lexicon.
WhatTheyThink runs on a combination of freemium and premium (ad supported). The majority of viewers are free forever (supported by both ads and premium member subscription). Online video games are another model where the majority of players play forever without spending any money, subsidized by those players who choose "premium" paid-for options.
The Web 2.0 software version of freemium interests me the most. There is a tremendous amount of free services available today via this model that provide real value for the long term for the majority of users. It runs the full gamut, from project management software such as 37 Signals' Basecamp to MailChimp's e-mail campaign software. I recently counted the number of freemium models I use today - the current total is about 50 services that I use on a semi-regular basis without paying anything. Watch the Land o' Freemium section of "The Web and Print" for reviews of the most valuable software tools you can use via the freemium model.
A successful freemium business model typically shoots for at least a 5% conversion of users to its "premium" offer. The key to this business model is multi faceted. Servicing the 95% has to be very close to free (think brilliantly easy-to-use software because support costs will kill you), and then think scale. This model only works if you can scale it and therefore the 5% conversion is a meaningful number. Some of these companies combine freemium with ad supported revenue streams, but there are 100% freemium business models working today where they are building successful business by giving away their services to 95% of their customers! – Amazing!
When change occurs, opportunity knocks and there is also fallout. One of the strangest terms I read in Anderson's book was "rapid market demonetization." The examples are startling. Consider the encyclopedia market as described by venture capitalist Josh Kopelman. Britannica was the leader of this $1.2 billion industry (1991). In 1993 Microsoft launched Encarta. De-monetization works like this: the encyclopedia market was cut in half in less than three years, "...every dollar of Microsoft's gain caused an asymmetrical amount of pain in the marketplace. They made money by shrinking the market."
Print (along with other atoms-based economies in the information business) is experiencing a form of demonetization; as new digital distribution companies are created the market for atoms-based information shrinks.
Print manufacturing will always be a physical product (atoms economy) but that doesn't mean that printers can't leverage the advantages of the digital economy in their businesses. Staying competitive in the atoms economy requires that you learn the efficiencies of the bits economy. The best published example I've heard of comes from the oldest continuously publishing newspaper in the world, The Daily Telegraph. I wrote about Toby Wright, CTO, in The Web and Print. He moved to a 100% SaaS software model with his IT infrastructure in the Cloud, drastically reducing costs and enabling The Daily Telegraph to focus on the core activity of creating valuable content for its readers. In order to remain competitive, atoms-based businesses must leverage all the advantages of the bits-based economy.
Change impacts each of us individually. The authors quoted in this article have enabled me to understand the roots of this transition from an atoms-based economy to a bits-based economy and how this impacts the print industry. Understanding this global transition helps me navigate better as well as to help others chart a course that inspires rather than paralyzes. What will your reaction to this change be? How can the industry collectively inspire the ability to embrace change rather than build defenses around yesterday? Food for thought ...

Tuesday, August 03, 2010

Global Digital Out-of-Home Media Forecast 2008-2012 AVAILABLE NOW

 Key Questions Answered:

  • What defines digital out-of-home media?
  • What historical trends have driven double-digit growth in the US and worldwide by region?
  • Which sub-segments will see the fastest growth and when?
  • What technological advances drive growth?
  • How will new measurement standards impact the industry?
  • How does National vs Local advertising share differ by sub-segment?
  • How much is being spent by ad categories by sub-segment?
  • What criteria are most/least important to buyers of video advertising networks?
  • What's the long-term growth potential for each sub-segment through 2012?
  • Who are the leaders, key players and emerging companies to watch?
  • How will the gold rush, shakeout, and anticipated breakout shape the future of the industry?

Global History, Spending, Trends & Analysis (click here for report)

As the global economy continues to weaken, traditional media advertising dollars continue their migration to alternative media, and specifically digital out-of-home (OOH), in the US and abroad, as the seminal transition taking place across the media landscape continues to accelerate.
This first-ever primary research into the global digital OOH market, reports rapid growth of 22% to $5.4 billion in 2007, and an anticipated increase of 13% to $6.1 billion in 2008. However, after growing at over 20 percent every year from 2002-2007, US growth in digital OOH media is expected to go through a shakeout, with a dip to 9.1% in 2009, bouncing back to 12.8% in 2010 as conditions improve. The US accounts for 40% of the global DOOH industry, but that percentage is expected to decline over time. Key international markets include the UK, Japan, France, Germany, Russia, and China, with the Chinese market benefitting from the impact and innovation of Olympic marketing.
The DOOH media sector, first identified and defined by PQ Media in 2007, helps advertisers engage consumers during their daily routines in captive environments, with innovative technologies such as digital billboards and video advertising networks in offices, retail, theater, and transit. Patrick Quinn, president and CEO of PQ Media has said, "Digital Out-of-Home media is emerging as a key component of a new advertising model as marketers search to engage and influence consumers at points of decision. Our research shows the timing in terms of the economy and shifting media landscape is propelling brands to embrace digital platforms."
This exclusive 125 page report is intended to provide media stakeholders with unique global strategies for first mover advantage and growth through its breadth of data, analysis and commentary on this potentially game-changing platform. It includes 24 tables & charts, more than 1,000 digital OOH providers identified by sub-segment, 600 from the US, as well as a convenient summary of the just released Out-of-home Advertising Bureau (OVAB) Audience Metrics Guidelines.

Global Digital Out-of-Home Media Forecast 2009-2014 new report available NOW

Global History, Spending, Trends & Analysis report available NOW (click here)

Amid a sharp downturn in global advertising spending and a decline in traditional out-of-home advertising in 2009, digital out-of-home media is among the fastest growing media in the world and will continue on an upward track in 2010, according to a new global forecast from PQ Media, the leading provider of media econometrics.
Throughout history, emerging media supported by strong audience metrics have consistently grown during economic recoveries after deep recessions. This was true for radio in the '30s and '40s, broadcast TV in the '50s, cable TV in the '80s and '90s, and Internet and search in the '00s. PQ Media data strongly suggest history will repeat itself in the case of digital out-of-home media, due in part to today's unprecedented media disruption and fragmentation, people consuming more media out of the home all day long, and with media stakeholders placing greater emphasis on audience measurement.
While the rate of growth has gone through a "gold rush" and a PQ Media predicted "shakeout" phase, with decelerated growth for the second consecutive year, the report anticipates U.S. spending will grow 2.0% to $2,469 billion in 2009, with worldwide spending up 4.7% to $6.69 billion. Starting in 2010, PQ Media forecasts digital OOH will move into a "breakout" phase and grow at a compound annual rate of 9.4% through 2014 in the U.S. and 10.1% globally. During the forecast period, many video advertising network and digital billboard sub-segments are anticipated to see double-digit growth in spending.
The digital OOH media sector was first identified and defined by PQ Media in 2007. The PQ Media Global Digital Out-of-Home Media Forecast 2009-2014 is the most comprehensive and respected source of strategic intelligence used by leading digital OOH operators, financial companies, brands and agencies, due to its breadth and depth of data and analysis.
The much anticipated 2009 edition covers 15 countries in the Americas, Eastern Europe/Middle East/Africa and Asia/Pacific; has been expanded to reflect input from more than 650 digital OOH companies; presents exclusive findings and predictive analysis and runs 185 pages with more than 30 data tables & charts, as well as the largest collection of digital OOH company profiles with contact information ever assembled. Detailed drill-down segment and sub-segment data from PQ Media's deep repository of proprietary spending and media usage databases provide media stakeholders with the essential planning tools for developing sound strategic initiatives in an evolving digital OOH media space.

Exclusive History, Spending, Trends and Analysis Available No Place Else:

  • Definitions & Segmentation:
    • Video Advertising Networks (VANs) – In-Theater, In-Retail, In-Office, In-Entertainment, In-Transit
    • Digital Billboards and Ambient Advertising – At-Road, At-Transit, At-Entertainment, At-Retail
  • US and Global digital OOH Media Spending Analysis 2004-2014
  • Global Regions Covered: US, Canada, Latin America, Western Europe, Eastern Europe/Middle East/Africa, Asia/Pacific
  • Countries Covered: US, Canada, Brazil, UK, Germany, France, Spain, Italy, Russia, Middle East & Africa, Japan, China, South Korea, Australia, India
  • Digital OOH Share of Overall Out-of-Home Media Spending
  • Top 20 Video Advertising Network Providers
  • Top 20 Digital Billboard Providers
  • Top 10 Trends Driving DOOH Going Forward
  • Digital OOH Spending by Company Cluster - Top 10, 11-25, 26-50, etc.
  • Share of Digital OOH Spending by Company Size - Over $100 Million, $50-$100 Million, etc.
  • Digital OOH Spending by Ad Categories 2009
  • Share of Digital OOH Spending by Segment
  • Share of Digital OOH Spending in 2009 - National vs Local
  • VAN Spending 2004-2014
  • Digital Billboard Spending 2004-2014
  • VAN Share of Digital OOH Spending 2009
  • Global digital OOH Media Spending Analysis - Americas, EMEA, Asia/Pacific
  • Global digital OOH Spending and Share by Region and 15 Selected Countries
  • Share of VAN Visitors with Income Over $100,000
  • Time Spent Annually with Media Per Person - 1984 vs 2008
  • Number of Visitors Per Venue Type, Visits Per Year and Avg. Minutes Per Visit
  • Number of At-Road Digital Billboards 2004-2014
  • Number of Commuters and Time Spent Commuting
  • Pro Sports Attendance 1985 – 2009
  • Estimated Consumer Interaction with VANs Per Month
  • Comparative CPM Rate Ranges by Medium

Appendix

Digital Out-of-Home Venue Types
Demographic Profile of Digital Out-of-Home Audiences
Share of Select Demographics by Select Venues
Digital Out-of-Home Company Profiles
Retailers with Digital Networks
Digital OOH Mergers & Acquisitions and Closures
Global Digital OOH Companies
SCREENS.tv - Digital Signage News http://www.screens.tv/

SCREENS.tv - Digital Signage News

SCREENS.tv - Digital Signage News: "– Envoyé à l'aide de la barre d'outils Google"

Thursday, July 29, 2010

Hello
 

So everyone and his (or her) dog seems to be talking about Twitter these days, right?
And while millions of people around the world are tweeting, twitting or twotting – many people still consider the Twitter groupies a bunch of twits.
Today I thought I'd send you 5 reasons why you should stay strong with your twit-mentality and avoid the Twitter bandwagon like the plague.
1) You Don’t Have Time
Your schedule is jam-packed every single day. You’re struggling to just break even with your task list. You barely have time to take a toilet break, let alone build relationships that could open you up into a whole new world of business connections and potential revenue.
2) You Have Enough Money
You’ve got exactly the right amount of money. You don’t want a single dime more. You want your income to stay exactly where it is, no ifs or buts. Any extra revenue to be made from forging  new business partnerships or projects on Twitter would just make you angry.
3) You’ve Got All The Friends You Need
You have got enough friends. They all have their place in your life and you don’t want to interrupt the pattern and add a single other friend to the mix. You don’t want to meet anyone from another country, share a conversation with a multi-millionaire or learn anything new from anyone – you’ll stick to your non-Twit friends, thanks.
4) You Don’t Want The Attention
You’re not interested in getting all the attention. You like being the mysterious underground player and letting the limelight-seekers’ websites receive the exposure. Let ‘em have it, you say, I’m fine with my current customer base. I don’t want anyone else to know about us who doesn’t already have our business card in their filofax.
5) You’re Not Interested In Breaking News
You hate breaking news. You hate having to hear about it before any of the news crews get abreast of it. You hate having to read about it as it’s happening. You like knowing that tomorrow, when its all died down, you will be able to read a brief summary of events from a single journalist in Washington as you eat your cereal.
Don’t worry, I totally understand where you’re coming from.
I mean… what does Guy Kawasaki, the NY Times or Oprah know about business or making money anyway...

{Side note: I sincerely hope you understood the sarcasm of this email and immediately sign up for a Twitter account and follow me at Lucien08}
Talk to you soon ;-)

Wednesday, July 28, 2010

Digital printer Second hand Market place

Scitex Pressjet II, 6-colour ready packed on pallets from 2006 full printing condition
60.000 euro ex works Europe perfect to add capacity to a current PJ owner


the high production wide format digital press, which promises to meet growing market demands for advanced color quality and multi-application flexibility.

Targeted at the graphic arts market, the Scitex Pressjet II represents a new generation of the Scitex Pressjet. Six-color printing (CMYK with the addition of light cyan and light magenta) make it possible to attain the highest image quality. Printing houses will also benefit from Onyx Postershop RIP, which offers a faster and simpler workaround, and provides new color management options.

Monday, July 26, 2010

Digital printer Second hand Market place

For Sale, ready packed (Printer must go urgently customer need space)

HP Scitex XL jet 1500 Digital printer second hand looking for a new home


Customer in west Europe

XL 1500 5m 8 colours upgraded till last model, and service Coverage since 23/08/2001 .

This info was validate with the EMEA Product support manager in that time.

Thursday, July 15, 2010

Wednesday, June 16, 2010

See you at : 1000 Party@FESPA the 22 June at 20H00


1000 Party@FESPA

Time: 19:30
Place: Augustiner-Keller ,
Arnulfstrasse 52 , 80335 Munich,
www.augustinerkeller.de
Who: All Customers

Monday, June 14, 2010

Let us meet at FESPA

We can meet at the HP booth Hall B2, Stand 120

the 24 at 14H

· 14:00 Meeting at HP booth with you

· 14:30-16:00 Presentation “HP solution package for CEE marketplace”

· 16:30-18:00 Come&See HP@FESPA (HP booth demos)

Saturday, May 29, 2010

A great week end learning how to build web site with traffic!

Friday, May 28, 2010

My favorite travel companion Richard Branson

An early start to launch our new round the world fares. Go We... on Twitpic

Is Bullishness at IPEX a Positive Sign?

By Dr. Joe Webb on May 25th, 2010

The reports from IPEX have been very enthusiastic. Most all reports from any show floor, in my 33 years in the industry, are positive, no matter what the facts seem to be. It’s our nature, especially when our industry’s owners and suppliers are all in one place. But these reports from IPEX seem to stand apart.

I was not there, nor have I ever been to an IPEX, so I can’t offer my own assessment. The idea of such bullishness it got me thinking (that’s usually dangerous).

What if the show really is a change in sentiment, and that sentiment is based on a true upward turn in the fortunes of print businesses. If so, then what was it that happened? Did anyone repeal the Internet, deflate the excitement of the iPad, and “unfriend” social media? Did print demand suddenly rise?

Of course, none of those happened, and all of those still and will affect our business.

Perhaps the industry may have right-sized itself. Weak print businesses have closed (even those who did not know that they were weak at the time), displaced workers took their skills elsewhere, and inefficient equipment sits idle or was scrapped. We won’t know if this has happened except in retrospect, but there is some reason to believe that these trends were underway in 2009. While print demand won’t come back, print profits can.

The number of workers in the industry declined for part of the year at a faster rate than print shipments fell. That means that the industry was finally getting down to a productive base that was more appropriate for demand levels. Prior to that, employee reductions were trending at a rate down that was less than shipments. Finally things may be more appropriately balanced. The industry finally made an annualized profit in the fourth quarter of 2009.

The decline in employees also means that there was a decline in the number of establishments. This was discussed in a recent chart. Weaker companies, prone to cut prices to stay busy, can survive in an environment where demand is flat or rising. Last year’s steep decline in shipments, however, may have been too much for them, especially if they had more debt than they should have.

While print prices are not rising, the healthier firms that have survived are in better position to cope with retrograde market prices than those who had heavy debt burdens.

Perhaps we have finally arrived at a point where we have a core set of healthier print businesses, who have absorbed the sales volumes of their departed brethren without their overhead costs. That’s they way it’s supposed to work. Even if those volumes are at disappointing prices, they are being added to firms that have already covered their fixed costs, and show profits when others did not.

When will we know? The full extent of government data about this period will not be available until 2012 or 2013; that doesn’t help us now. We are able to make estimates with some assumptions based on other data later this summer. If this scenario is true, it also means that a positive capital investment period for the print industry may start again soon. Wouldn’t that be nice?

- Sent using Google Toolbar"

Wednesday, May 26, 2010

Elements: The Only 6 Elements of All Marketing Programs « GoMarket.me

Elements: The Only 6 Elements of All Marketing Programs « GoMarket.me: "Elements: The Only 6 Elements of All Marketing Programs

There are basic elements that consist in all Marketing Programs, at the heart of all Marketing efforts. Know that there are whole sciences dedicated to each these elements alone, and that these are simple high-level overviews.

1. Audience: Who is to Hear the Message?

a. The audience can be broad or narrow, but a targeted audience is best. Sometimes it’s an in-house email list, sometimes it’s the audience of a website, or a highway, or a neighborhood. And it can be everything in between. The best Marketing Programs have an audience that has been targeted – that is, selected based on certain criteria. The criteria can be demographic (age, weight, hair color, etc.), geolocated (residence, work location, on-demand location), or behavioral (based on actions an audience member has taken.) etc. There are many ways to target an audience. And remember, there are many paths to the same destination.

2. The Message: What to say and How to Say it.

a. This is where Marketing Communications comes in. There is an art form at best, and conversation at least. It is the who, what, when, where and why.

3. The Deliverables.

a. This is the creative package. It is the email, the text message, the banner ad, the print ad – whatever the campaign is, this is the visual/audio piece intended to carry the message through the channel.
b. This is also known as “the creative.”
c. This is a true art form. I have had the pleasure of working with some amazing creative teams. To me, they are essential, balancing the art and the science of the deliverable.

4. The Channel: How to Share the Message with the Audience.

a. Channels are what you may hear of most often. I once spent a 1.5 years focused soley on one channel: email. Other channels include, but are not limited to: search engine marketing, email marketing, advertising (online/banner, video/tv, print/direct mail/mobile), text messages, social media, events, product review, shopping portals, the shoe bins at the airport. . . and the list goes on and on.

5. The Call to Action.

a. The end goal. This is what you are asking the audience to do. This action is also known as “conversion.” When you hear: “Did the campaign convert?” you are being asked “Did the audience take the action you wanted them to?”
b. Common call-to-actions are: “Buy Now,” “Click Here” “Sign Up Now” “Come to Our Event” “Learn More” “Visit Us” “Read On” etc.

6. The Measurement: Was it Successful?

a. Metrics, metrics, metrics, a.k.a. Tracking, a.k.a Numbers. The numbers tell a story. Was the combination of the Message and the Channel motivating enough to take action? Was the Call to Action clear, concise and up front? Was the design of the message and the channel putting enough emphasis on the call to action? Every Marketing Program is measured differently. Every channel has a different industry average metrics.

Notice there is no mention of product. For all intensive purposes, the “product” is rolled into the message and into the call to action. The “product” in a campaign can be anything. Truly. It can be events, papers, hard products, soft products, services.

– Envoyé à l'aide de la barre d'outils Google"

Monday, May 10, 2010

To receive answers in life, you must begin to ask.
A basic step to success in life, Business and Philosophy Lucien Moons Business and Personal Brand Accelerator
Lucien Moons Business Accelerator take away from his last training: Success is all about your attitude http://tinyurl.com/36ehgcc
Try not to become a man of success, but rather try to become a man of value.

Saturday, May 01, 2010

From Barcelona Meeting:Lucien Moons International Business Accelerator expert AND Personal Branding Accelerator Empower In Company lead Generation Personal Brand Teams. Join the Lead Generation and Career Building new Wave. link with me to learn more in coming months. http://tinyurl.com/2bgv6ka

Friday, April 16, 2010

Business Opportunity. Investment in Emerging Market.For serious investors/or high retrun investment Funds

One of my client is opening their capital to accelerate their growth and West Europe expansion.They received a large EEC funding to invest in new technology, but look for a partner to develop the company infrastructure.
If you are interested please contact me.

Thursday, April 01, 2010

http://tinyurl.com/6yt3zq Business Trend idea Spoonflower lets users design and print their own fabrics for USD 18 per yard with no minimum order. When Spoonflower comes out of beta, it plans to allow fabric designers to sell their fabrics on the site.

Monday, March 29, 2010

Recently, a client asked me whether it would be a good idea to lower prices in order to generate more sales

Solving the Price Puzzle

By David Dodd on March 14th, 2010
Recently, a client asked me whether it would be a good idea to lower prices in order to generate more sales.  I suspect that many printers have thought about the same question more than once.
Decisions about increasing or reducing prices are inevitably complex and difficult to make unless, of course, your prices are very low or very high relative to others in your market.  It’s tough to pull the trigger on a price change because of the inherent uncertainty about what the financial impact of the change will be.  If I lower prices, will I generate enough new sales to increase my profits?  If I raise prices, will I lose so much business that my profits will be harmed rather than helped?
These questions are extremely difficult to answer.  In fact, to answer them accurately, you have to know what the “elasticity of demand” is for your company’s products and services.  And unfortunately, your company’s elasticity of demand isn’t something you can find in your local library or look up on the Internet.
The good news is that there is a simple calculation that can help owners and managers make more rational decisions about price changes.  The calculation is simple because it doesn’t try to predict what will happen if you raise or lower prices.  Instead, this calculation describes what must happen for a price change to be profitable.
Specifically, this calculation can answer two questions:
  • How much would I need to increase sales volume in order to profit from a specified price reduction?
  • How much could my sales volume go down before a specified price increase becomes unprofitable?
The measure of “profit” used in this calculation is contribution margin (sales minus variable costs).  This calculation can be used to evaluate across-the-board price changes and price changes that apply to major segments of your business.  It cannot be used for individual jobs.
The calculation uses the actual contribution margin (expressed as a percentage of sales) generated during a base period (usually a year).  When you reduce selling prices, the contribution margin goes down, and new sales volume must make up for that decline before profits will be improved.  On the flip side, your contribution margin goes up when you increase prices, and you can afford to lose some sales volume before profits are impaired.  This calculation will tell you where those “breakeven points” are.
The formula is:  -(Price Change) / (Contribution Margin + Price Change)
To give a simple example, suppose that your contribution margin during the base period was 80% and that you are considering a 10% price reduction.  How much will your sales volume need to increase for the price reduction to be profitable?  The answer is 14.3%, calculated as follows:
Breakeven Sales Volume Increase = -(-10%) / (80% + (-10%))                            
Breakeven Sales Volume Increase = 10% / 70%
Breakeven Sales Volume Increase = 14.3%
If your company had sales of $5 million during the base period, you would need to increase sales by more than $714,286 for the 10% price reduction to be profitable.
I’ve created a simple Excel worksheet to calculate these breakeven points.  If you’d like a copy, e-mail me directly at lucien@lucienmoons.be

Saturday, March 27, 2010

Do You Know Your Z Score? You Should!

Hello

With the reduced turn over you experience 

to day, this tool can help, looking in your
business future and take actions TODAY,
to have a FITTER business.

Lucien Moons 

International Business Accelerator Expert.


By David Dodd on March 25th, 2010

It’s no secret that the past 12 to 24 months have been especially difficult for many printing companies. Dr. Joe Webb is estimating that the printing industry lost 2,844 firms in 2009. Bankruptcies, foreclosure auctions, and other closures have been well documented in the press as well as by other trade publications.

Having a clear picture of your company’s financial health is always important, but it becomes essential when business conditions are difficult and the margin for error is reduced. And while no single tool or formula provides a complete picture of financial health, one popular measure is known as the Z Score.

The Z Score was developed in 1968 by Edward Altman, a financial economist and professor at NYU. The original objective was to provide a way to assess creditworthiness. Since that time, the Z Score has become a popular method of analyzing a company’s financial health and estimating the short-term risk of bankruptcy.

The Z Score isn’t perfect, but when it was initially tested, it was found to be 72% accurate in predicting bankruptcy within two years. Subsequent testing found that the Z Score was 80%-90% accurate in predicting bankruptcy within one year.

The Z Score combines five common financial ratios. Each of these ratios is multiplied by a weighting factor developed by Professor Altman. The values obtained are then added together to determine the Z Score.

The specific ratios and weighting factors for privately-held manufacturing firms are shown below:

* (Working Capital / Total Assets) X 0.717
* (Retained Earnings / Total Assets) X 0.847
* (EBIT / Total Assets) X 3.107
* (Book Value of Equity / Total Liabilities) X 0.420
* (Net Sales / Total Assets) X 0.998

A Z Score of above 2.90 indicates that bankruptcy is not likely. A score that is lower than 1.23 indicates that bankruptcy is a strong possibility.

Your Z Score should be calculated on a quarterly basis as one part of a comprehensive review of your company’s financial performance. This quarterly financial health “check-up” needs to become a standard component of your management routine. As I noted earlier, when times are tough and the margin of error is small, it’s more important than ever to monitor the financial health of your company in a thorough way, on a regular basis.

If you don’t have the time or resources in-house to perform this kind of financial review, you should consider getting assistance. It doesn’t have to be costly or disruptive, and with online collaboration tools, it can usually be handled remotely.

I’ve created an Excel-based Z Score Calculator. If you’d like a copy of this worksheet, e-mail me directly at ddodd(at)pointbalance(dot)com.
what was new in Prague?Speed up your print offers with web2.0 http://tinyurl.com/ybox6op

Thursday, March 25, 2010

"Go for the moon. If you don't get it, you'll still be heading for a star."

Tuesday, March 23, 2010

We only get one life, and the urgency of getting on with what we’re meant to do increases every day

Sunday, March 21, 2010

Wednesday, March 17, 2010

Monday, March 15, 2010

“When you do nothing, you feel overwhelmed and powerless. But when you get involved, you feel the sense of hope and accomplishment that comes from knowing you are working to make things better.”

Friday, March 05, 2010

Wednesday, March 03, 2010

"Character is the result of two things: mental attitude and the way we spend our time"

Wednesday, February 24, 2010

Business Opportunity
(http://ping.fm/ERok3)
check this link
http://ping.fm/zrm6Q
PaperG is an advertising technology company that automates local ad creation, sales, and management for online publishers, enabling them to produce cost efficiencies and increase revenue.
Maybe a business opportunity in your countries for digital printer, adding delivery of banners and roll up with the online ad??

Sunday, February 21, 2010

Invitation To VIP industrial printing Days
(http://ping.fm/tcnHl)

The HP Scitex FB7500 Printer is a productive digital UV printer designed for close-view, high-quality applications such as POP/POS.

What sort of companies can most benefit from the HP Scitex FB7500 Printer?

Screen and offset printers and large digital printers focused on indoor applications can gain most benefit from the productivity, quality and versatility strengths of the HP Scitex FB7500 Printer
Hello welcome to my Ping application.

Wednesday, February 17, 2010

Lucien Moons helps the Worldwide adoption of the HP Scitex FB7500

Digital Printing Expo - next edition 10-12 March Poznan

You are welcome to participate in the Digital Printing Expo - specialized salon of next edition of the Euro-Reklama trade fair, which will take place from 10 - 12 March 2010 in Poznan in the complex modern pavilions of Poznań International Fair.

Poznan spring meeting the advertising industry occupy first place in the calendar of major events for the exhibition sector, out-of-home media in Poland. Large Format Printing and Digital Printing Expo are:

Large print Print advertising Materials and equipment for the production of advertising Advertising services Publishing and specialized portals Digital Printing Expo is a unique place for meetings with customers and business partners and the opportunity to acquire new business contacts. It is expected that the next edition of the Poznań fair publicity to visit more than 20 000 professionals representing:

* Advertising Agencies
* Agencies BTL
* Media houses
* Local governments: promoting sections of cities, municipalities and counties
* Regional tourism organizations
* promotion of political party offices
* network clients - such as chains, petrol stations, telephone operators
* Study graphic and printing
* Environment marketing: marketing departments and advertising companies from different industries


Fair Euro - Reklama 2010 will not only offer a platform for the presentation of the latest market, but also a source of expertise and opinion of the place of creation. Rich program of panels and conferences with regulators of the advertising market in Poland and the institutions that will operate on him to perform at the highest level of debate.

At the same time, the Poznań International Fair will take place:

Salon of Marketing Communications - Visual Expo

Poznan Fair Media Expo

Join us!

Friday, December 25, 2009

Global Digital Out-of-Home Media Forecast 2009-2014 AVAILABLE NOW

Global History, Spending, Trends & Analysis


Amid a sharp downturn in global advertising spending and a decline in traditional out-of-home advertising in 2009, digital out-of-home media is among the fastest growing media in the world and will continue on an upward track in 2010, according to a new global forecast from PQ Media, the leading provider of media econometrics.
Throughout history, emerging media supported by strong audience metrics have consistently grown during economic recoveries after deep recessions. This was true for radio in the '30s and '40s, broadcast TV in the '50s, cable TV in the '80s and '90s, and Internet and search in the '00s. PQ Media data strongly suggest history will repeat itself in the case of digital out-of-home media, due in part to today's unprecedented media disruption and fragmentation, people consuming more media out of the home all day long, and with media stakeholders placing greater emphasis on audience measurement.
While the rate of growth has gone through a "gold rush" and a PQ Media predicted "shakeout" phase, with decelerated growth for the second consecutive year, the report anticipates U.S. spending will grow 2.0% to $2,469 billion in 2009, with worldwide spending up 4.7% to $6.69 billion. Starting in 2010, PQ Media forecasts digital OOH will move into a "breakout" phase and grow at a compound annual rate of 9.4% through 2014 in the U.S. and 10.1% globally. During the forecast period, many video advertising network and digital billboard sub-segments are anticipated to see double-digit growth in spending.
The digital OOH media sector was first identified and defined by PQ Media in 2007. The PQ Media Global Digital Out-of-Home Media Forecast 2009-2014 is the most comprehensive and respected source of strategic intelligence used by leading digital OOH operators, financial companies, brands and agencies, due to its breadth and depth of data and analysis.
The much anticipated 2009 edition covers 15 countries in the Americas, Eastern Europe/Middle East/Africa and Asia/Pacific; has been expanded to reflect input from more than 650 digital OOH companies; presents exclusive findings and predictive analysis and runs 185 pages with more than 30 data tables & charts, as well as the largest collection of digital OOH company profiles with contact information ever assembled. Detailed drill-down segment and sub-segment data from PQ Media's deep repository of proprietary spending and media usage databases provide media stakeholders with the essential planning tools for developing sound strategic initiatives in an evolving digital OOH media space.

Exclusive History, Spending, Trends and Analysis Available No Place Else:

  • Definitions & Segmentation:
    • Video Advertising Networks (VANs) – In-Theater, In-Retail, In-Office, In-Entertainment, In-Transit
    • Digital Billboards and Ambient Advertising – At-Road, At-Transit, At-Entertainment, At-Retail
  • US and Global digital OOH Media Spending Analysis 2004-2014
  • Global Regions Covered: US, Canada, Latin America, Western Europe, Eastern Europe/Middle East/Africa, Asia/Pacific
  • Countries Covered: US, Canada, Brazil, UK, Germany, France, Spain, Italy, Russia, Middle East & Africa, Japan, China, South Korea, Australia, India
  • Digital OOH Share of Overall Out-of-Home Media Spending
  • Top 20 Video Advertising Network Providers
  • Top 20 Digital Billboard Providers
  • Top 10 Trends Driving DOOH Going Forward
  • Digital OOH Spending by Company Cluster - Top 10, 11-25, 26-50, etc.
  • Share of Digital OOH Spending by Company Size - Over $100 Million, $50-$100 Million, etc.
  • Digital OOH Spending by Ad Categories 2009
  • Share of Digital OOH Spending by Segment
  • Share of Digital OOH Spending in 2009 - National vs Local
  • VAN Spending 2004-2014
  • Digital Billboard Spending 2004-2014
  • VAN Share of Digital OOH Spending 2009
  • Global digital OOH Media Spending Analysis - Americas, EMEA, Asia/Pacific
  • Global digital OOH Spending and Share by Region and 15 Selected Countries
  • Share of VAN Visitors with Income Over $100,000
  • Time Spent Annually with Media Per Person - 1984 vs 2008
  • Number of Visitors Per Venue Type, Visits Per Year and Avg. Minutes Per Visit
  • Number of At-Road Digital Billboards 2004-2014
  • Number of Commuters and Time Spent Commuting
  • Pro Sports Attendance 1985 – 2009
  • Estimated Consumer Interaction with VANs Per Month
  • Comparative CPM Rate Ranges by Medium

Appendix

Digital Out-of-Home Venue Types
Demographic Profile of Digital Out-of-Home Audiences
Share of Select Demographics by Select Venues
Digital Out-of-Home Company Profiles
Retailers with Digital Networks
Digital OOH Mergers & Acquisitions and Closures
Global Digital OOH Companies

all right belongs to

PQ Media LLC
Two Stamford Landing
Suite 100
Stamford, CT 06902

Thursday, April 30, 2009

2009 04 30 A Change is Gonna Come

In these very hard economical times, we feel a little unsecure sometimes. When it happens to me i listen to this optimistic songs and i feel immediately better. To day i want to share it with you, because i will always "stand by you" (Put the sound on and enjoy)Talent is everywhere we just need to see it.


Playing For Change | Song Around The World "Stand By Me" from Concord Music Group on Vimeo.

Sunday, March 22, 2009

Digital Printing 2009 Beyond the Technology Enablers


Technology Enablers

What you should know before investing in new presses in 2009

When are the projects taking place: end 2008/early 2009

Project Structure & Deliverables
• Research of markets, technologies, economics and buyers; Deskwork plus Interviews
• Written report with executive summary;
• Workshop for participant companies;

Background

2008 was a year of opportunity for digital printing. There is a glut of ‘shallow’ reports in the printing
sector. We shall summarise quantitative market growth forecasts. But there is a gap in the market for
readable, clear, in-depth sales and marketing structure information. Such information will provide a
new perspective, highly-actionable material for participants. When can digital be used from a technical
and economic perspective as of now? What is the ‘psychology’ underpinning the process of change
to digital from analogue? If the technical and economic performance is right, as we’ll determine in the
Total Cost of Ownership / ROI models presented, why won’t people take up digital systems? These
questions though important, are generally left unmentioned, or at least unexplored. Do we understand
the performance, economics and decision-making of digital within the broad context of the entire
business unit, and the interests of individuals in the corporate environment, who are responsible for
changing over to digital? Putting this together may reveal more about why some companies will not make the investment in a printing system. It may take us beyond the technology enablers.

Premise
• Potential buyers and users of digital printing systems don’t have enough information and
understanding to know that digital printing may be good for them. Those that do, may be inhibited.
Aim
• The report forms the basis of a valuable marketing strategy to suppliers of digital systems. Explain
remaining barriers to adoption of digital printing systems, which will benefit printing system,
printhead and ink suppliers responsible for tactical marketing and selling.
• Write report, an authoritative, independently-produced body of mainly primary market knowledge.
• Take on board issues around organisational and individual behaviour, and management practice.
How do individuals with responsibility for buying and running the printing systems think and act?
Under what conditions do they work?
• We hope that with your early support, this will become the private industry reference on these
issues.
source Cambridge Investment Research Ltd

What can we do, to "ride" on this crisis?


I have been asked this question in every meeting since December?


And after looking and talking with other business owner, surfing the Internet i can see one of the answers that seems working:

Never Stop Selling


Another business I know has recently had “the best January ever”. The reason: they suffered a down-turn in business several months ago, went back to basics and came out marketing and selling targeting old and new customers with new propositions (better ways of taking their existing products and services to market in the current climate).

What to do?

1.

Never stop selling
2.

Listen to the people that you speak to – if they are not buying what you are promoting:
1.

What are they considering buying that you already offer?
2.

What might they buy (rent, lease, ….) that you could easily offer?
3.

Refine your targeting – speak to different people
4.

Keep positive

Things to consider


*

If changing customer requirements take you too far from your comfort zone, look for alliances and other mechanisms to satisfy these opportunities with minimum risk;
*

Use Segmentation tools (or get someone to do it for you) to better understand your suspect universe;
*

Additional products with lower costs or new processes;
*

New, higher value, products / services may be appropriate for some.

A Simple Exercise

*

List 5 things that are preventing you from winning enough good quality business.
*

Against each of the 5 items on your list, assign a score from 1 – 10 where 10 is something you can directly control and 1 is something over which you have no control at all.
*

Now, re-write your list in descending order of assigned scores.
*

Plan time for each of the top 3 on your new list.


Enjoy the findings and go implement your new success formula.

Sunday, March 30, 2008

HP Unveils New Technologies and Products, Pre-Drupa


HP Latex Inks, three new Indigo presses, SmartStream workflow, and more.
In Tel Aviv, Israel, at a preview event for the upcoming Drupa tradeshow, HP announced a release of graphic-arts technologies and products designed to improve the speed and reduce the cost of digital printing. The rollout supports HP’s Print 2.0 strategy, which is geared around capturing more digital pages from the analog print market and enabling print shops to take advantage of new market segments and business opportunities.

Release highlights include:

• New HP Latex Printing Technologies: The new water-based HP Latex Inks are designed to "offer an environmentally responsible large-format printing alternative for a wide variety of outdoor and indoor applications" and produce odorless prints (although some substrates may have inherent odor, HP points out). The latex inks will work with new printers that will be announced at Drupa in May; printers using the new inks will use internal heaters to dry and cure the latex polymer film. The latex inks will work with a broad range of HP and non-HP large-format media, and will provide display permanence up to three years unlaminated (results may vary based on media performance).

• Three new HP Indigo press models – the HP Indigo 7000, HP Indigo W7200, and HP Indigo WS6000: The first of these new presses available to the market will be the Indigo 7000 in June. Variable-data capable, the press runs at speeds of 120 four-color pages per minute and is aimed at general commercial printing, photo merchandise production, and other high-volume applications. The Indigo WS6000 and W7200 models are web-fed digital presses designed for industrial and commercial applications, respectively, while the WS6000 model is a label and packaging press targeted at users with significant volumes of medium- and short-run jobs. The WS6000 is expected to be available in early 2009, and the WS7200 is expected to be available in the second half of 2009.

• Also on the Indigo side of things: HP has enhanced the Indigo press 5500, allowing greater productivity with an additional feeder, an in-line connection to the HP Indigo UV Coater, and a kit for enabling printing on thicker media. And the Indigo ws4500, a digital label press, is now offered with an EskoArtwork digital front-end to enhance both quality and productivity.

• The HP SmartStream Digital Workflow Portfolio, the company’s first graphic-arts workflow portfolio: The company's Indigo presses will be the first hardware devices to employ the HP SmartStream Digital Workflow Portfolio, an open environment designed to meet a broad range of market segments and application needs and provide workflow management from job creation to fulfillment. Combining SmartStream and partner components will result in specific solutions that are customizable and scalable to the unique business needs of print service providers operating in key market segments, such as general commercial printing, direct marketing, publications printing, photo merchandise, and labels and packaging. Future additions to the HP SmartStream portfolio will offer workflow components for other HP segments, including HP Scitex, HP Inkjet High-Speed Production Solutions, and HP Designjet, the company reports.

• The HP Inkjet Web Press: A high-speed color digital printing platform, the Web Press is capable of printing in full color on rolls up to 30-inches wide at 400 feet per minute (122 m/min.). It's compatible with a wide range of uncoated media to enable efficient printing of book signatures, full broadsheet newspapers, and other documents. It's expected to be commercially available in the second half of 2009.

HP
www.hp.com

Monday, February 18, 2008

Digital Textile Printing Driven by Signage By Lucien Moons

Digital Textile Printing Driven by Signage
and Now Expanding Into New Areas

The digital printing of textiles has been going on since the mid 90s with electrostatic (e-stat) and inkjet printers, either by direct printing (in the case of inkjet) and via dye sublimation transfer (inkjet and e-stat). Today advances in inkjet printers, e.g., direct to fabric sublimation printers, combined with growth in textile applications such as soft signage and apparel are driving the market for digital textile printing. I.T. Strategies estimates that in 2005, 2,300 dedicated digital textile printers (units) produced more than 900 million square feet of digitally printed textiles. Of this 75% (just under 700 million square feet) was signage related and 25% (233 million square feet) is in newer application areas such as interior furnishings and apparel. By 2010, I.T. Strategies expects that digitally printed textiles will grow at a CAGR of 19% to more than two billion square feet printed on more than 5,000 dedicated digital textile printers.

Soft signage is a sub-segment of the larger signage market. The reasons for the success of digitally printed soft signage are: that it is different from paper/vinyl and therefore will get the viewer's attention; fabric signage creates an upscale impression; reduced costs related to the fact that fabric is lightweight and flexible meaning that shipping costs are lower; and finally, if the competition has it, then other shops have to follow. The growing competition in the signage market has caused some Print-for-Pay shops to look to other areas for growth. One of those areas is decorative products. Technically speaking it is a relatively small jump from advertising-related signage into these new applications.

According to Patti Williams, Consulting Partner at I.T. Strategies, "The market for soft signage has been around for more than seven years and is fairly well understood. Newer and less understood is the market for digitally printed textiles for non-signage applications. In this area some of the drivers include: the value of brand as companies such as Herman Miller and Steelcase use digital printing to customize textile-based office structures with a customer's brand or logo; new systems of parallel, low-throughput inkjet printers printing simultaneously, such as the DPA system developed by Stork; Italian companies using inkjet printers to respond to Chinese competition; and designers and crafters entering the market and making investments in inkjet textile printers such as the DuPont Artistri."


source IT startegies

Sunday, December 30, 2007

BEAMZONE - OUT OF HOME featured by Lucien Moons Business Accelerator


The combination of classical Out of Home Advertising Media and Blue tooth Marketing offers the possibility to interact with customers at high frequented public places. Applying Blue tooth Marketing in addition to a conventional Out of Home campaign the impact of the campaign can be raised to new dimensions and a new contact quality will be generated.

An increased brand-impulse can be reached by intelligent end effective advertising space solutions.

Create new brand-experiences and realize innovative Out of Home advertising-concepts thanks to beamzone Bluetooth Marketing Technology!

Work together with well-known companies and agencies of the Out of Home industry:

Ströer, JC Decaux...

Thursday, December 13, 2007

Merry Christmas enjoy this great song


I want to share with you a song written by Bob Geldof and Midge Ure in 1984 specifically to raise money for Ethiopian famine relief. The original version was produced by Midge Ure and Trevor Horn, and released by Band Aid on November 29, 1984. In late 1984, a BBC report by Michael Buerk was aired highlighting the famine that had hit the people of Ethiopia.

Do They Know It's Christmas?

Let us reflect in 2008 what we could do, even a small act to help, in our countries, in our town, in our neighborhood a person or a family in need.

A good sales person, is a prepared sales person.

Whether you're a Junior or a Senior salesperson, if the art of selling is close to your heart, mysellingskills is for you. mysellingskills is an interactive way to become a real pro... or to stay one. It was developed by a successful team of salespeople and experienced e-learning professionals.

In 6 chapters of do’s and don’ts and tips and tricks, the following aspects of the face-to-face selling process are covered:

• The best way to open a sales talk
• Asking the right questions
• Using the right arguments: the customer's
• How to handle objections
• Selling your price
• Five ways to close a deal